Supply chain finance best practice
Most corporate treasurers have run an SCF programme — or at least heard the pitch.
Yet a striking number of programmes under-deliver, perhaps reaching only a fraction of the supplier base and generating far less value than they should.
Understanding why starts with what a typical programme actually looks like - and that guides us naturally towards what should be supply chain finance best practice.
The challenges faced by most SCF programmes
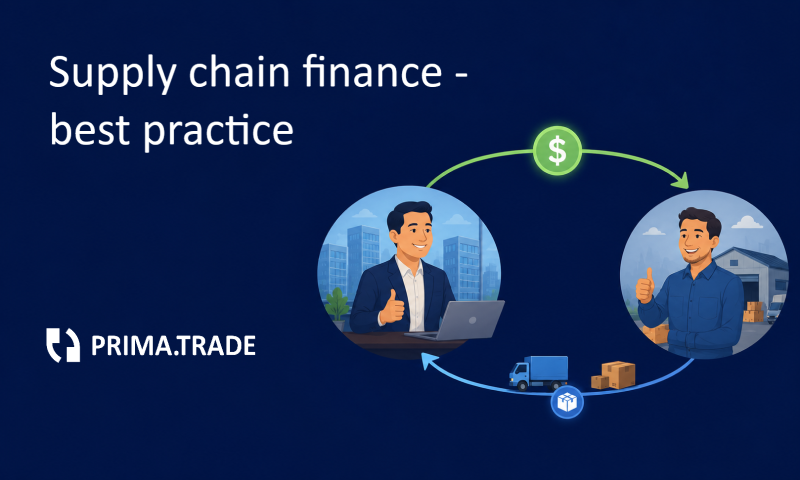
In a standard setup, a buyer works with a bank or platform to let approved suppliers receive early payments on invoices at a discount reflecting the funding cost, which is based on the buyer's credit rating.
The buyer extends payment terms;
The funder bridges the gap;
The supplier gets cash sooner;
On paper, everyone wins.
In practice, four structural problems get in the way.
The program does not reach many suppliers
Most programmes are built around larger suppliers - who may also be independently creditworthy and therefore not valuing liquidity support. The long tail — smaller suppliers, SMEs, international vendors — can be excluded.
In many businesses, that means the majority of suppliers by count see no benefit, and the excluded suppliers are typically those who would value SCF support very highly.
Invoice approval happens too late
SCF is triggered by approved invoices, but approval often runs weeks after goods have shipped. By the time a supplier can access early payment, much of the payment cycle has already elapsed. The financing window shrinks; so does the value.
There is no win for procurement
Procurement owns the supplier relationships but may see no direct return from a traditional SCF programme. The working capital gain goes to treasury; the finance charge goes to the bank. Asking procurement to champion a programme they don't benefit from can lead to push back and low engagement from suppliers.
Long tail suppliers are paid by card — expensively
Commercial cards offer the buyer a rebate, but net of charges it's modest. The supplier absorbs an acceptance fee that is typically higher than a negotiated early payment discount would be. Both sides get a worse deal than a well-designed SCF alternative would deliver.
What to do? Design for suppliers first
Programme success is determined by supplier utilisation — and utilisation is driven by supplier benefit, not buyer benefit.
Moreover, the accounting treatment that most buyers seek is based on the fact that this is a supplier financing, voluntarily used by suppliers - and not something that is mandated and controlled by the buyer.
Buyers capture value when suppliers participate.
Suppliers participate when the programme genuinely works for them.
The key question is not "what does the buyer need?" but "what does each supplier actually want?".
What suppliers need depends on the supplier type
International suppliers
Shipping cross-border, often weeks before payment is due, means suppliers want cash at the point of shipment.
They have documentation available to evidence their shipment — bills of lading, packing lists, inspection reports, commercial invoices — and are willing to upload these to a platform if it means they can get paid immediately.
A "Cash Against Data" model, where early payment is triggered by consistent shipment data directly matched to purchase orders meets this need.
Domestic and landed suppliers
They have a different profile. There are no shipping documents to upload. Their invoices arrive at the same time as the goods are delivered and can get posted quickly to the buyer's ERP.
What they want is simple: invoices that are quickly approved, click to draw an early payment.
A best-practice programme runs both models in parallel:
cash-against-data for international suppliers,
ERP-approved for domestic suppliers.
Each supplier gets the experience suited to their business. The buyer gets full supply base coverage.
Supply chain finance best practice - "in practice"
Early payments are truly early
Many buyers already have automated invoice approvals, which can be fine for domestic and landed suppliers but are usually too slow for cross-border.
When the approval process is slower than needed, best-practice programmes include:
a self-contained way to offer early payments without waiting for the ERP.
The best of both worlds is then available:
where needed, suppliers can access the self-contained route - and
otherwise they simply wait for the ERP to get there.
This can be organised without expensive IT or process re-engineering - just good programme design.
Procurement is a direct beneficiary
SCF funding costs are usually lower for suppliers than their own cost of money - so there is a win here. This can be captured by early payment discounts and the best SCF platforms enable this, creating the legal agreements, payment adjustments and account postings automatically in support.
When early payment discounts flow back as a reduction in cost of goods, procurement has a direct win.
Treasury and procurement are suddenly aligned around the same goal: more suppliers on the programme, paid earlier, generating bigger discounts. That internal alignment is one of the most underrated drivers of programme scale.
SCF can replace cards for the long tail
With a mixed-model platform that serves domestic suppliers as simply as international ones, the card programme becomes hard to justify.
A card rebate might return 0.5–1% to the buyer, net of charges of 2%+.
An early payment discount negotiated directly with a supplier — even a small one — can be materially larger, flows straight to cost of goods, and doesn't involve paying card network fees.
The supplier accepts an early payment discount rather than paying a card acceptance fee.
Both sides win because the expensive network charge is avoided - so
the buyer gets the benefit of an early payment discount that exceeds the card rebate,
the early payment discount accepted by the supplier is lower than the charge from the card provider.
Outcomes — traditional vs best practice
A well-designed programme delivers across four dimensions:
working capital improvement through extended DPO;
cost of goods reduction through early payment discounts to procurement;
supplier financial resilience through reliable early payment; and
better reporting / controls via the supplier data the process generates.
The scale difference is significant.
A conventional programme might reach fifty or a hundred suppliers. A best-practice programme built on these principles can serve hundreds or thousands — generating multiples of the economic value.
That scale is only achievable when every supplier type finds the programme accessible and genuinely useful.
Supplier benefit drives utilisation. Utilisation drives value. Value is what makes the programme worth running.
Continue the discussion
PrimaTrade enables you to extract the value already sitting in your supply chain by implementing SCF programs that meet the supply chain finance best practice guidelines.
If you’d like to see how supply chain finance could work for your business, we would be glad to talk: